Assumable Mortgage Homes for Sale in Greeneville, Tennessee (TN)
Search active homes in Greeneville, TN with low-rate assumable FHA, VA, and USDA loans (2.25%–4.25%). Use our interactive equity gap and 2nd-loan calculator to slide your down payment, estimate local property taxes (Greeneville Area · 0.64%/yr), and get quotes from lenders serving Greeneville.
Shopping for a Sub-4% Home in Greeneville, TN?
Compare FHA/VA assumption pre-approval, 2nd-position equity gap financing, and daily alerts for newly listed sub-4% homes in Greeneville, TN.
Assumable Mortgage Scenarios in Greeneville & Tennessee
View All Live Listings in Greeneville, TN →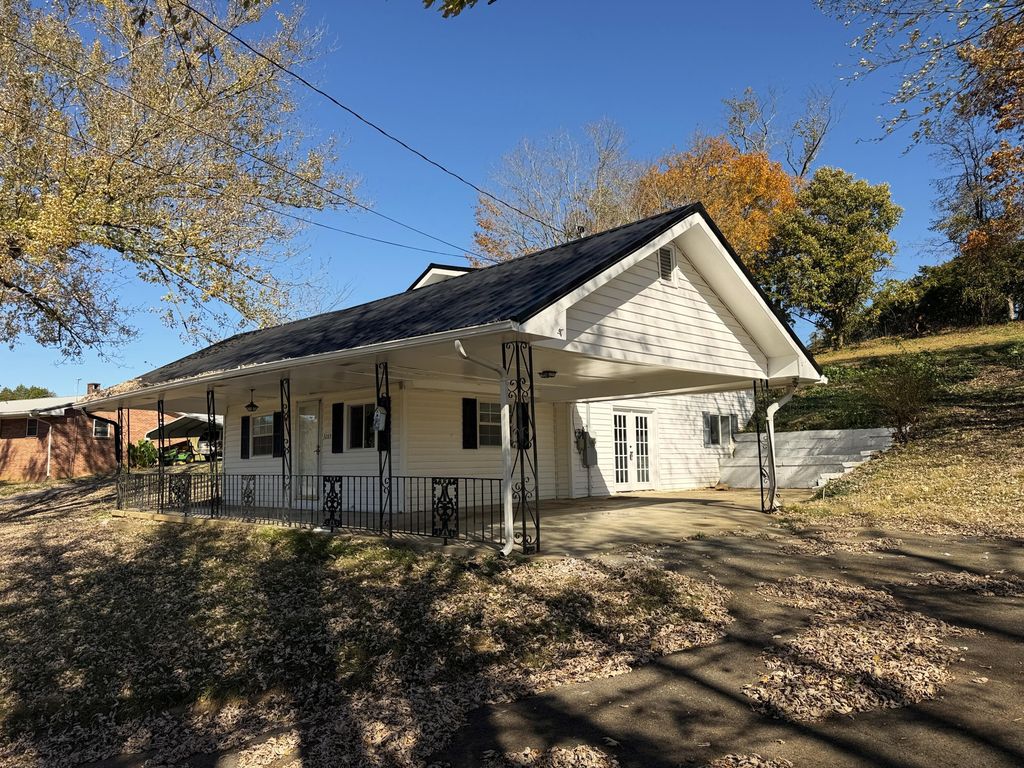 VA 3.75% AssumableSave -$957/mo
 VA 2.85% AssumableSave -$710/mo
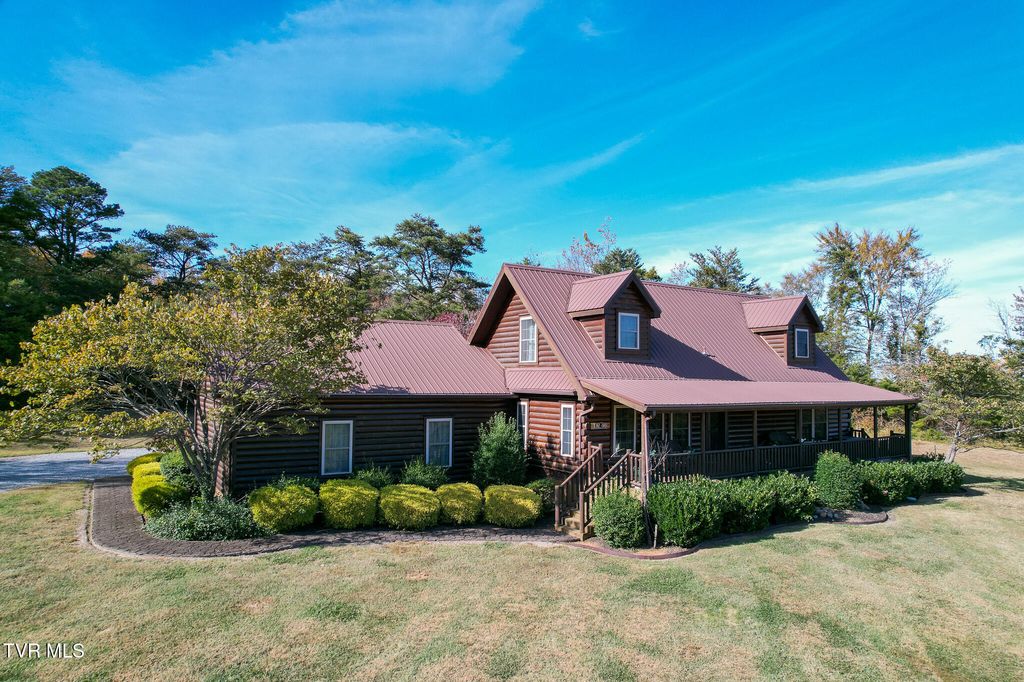 VA 2.75% AssumableSave -$2,437/mo
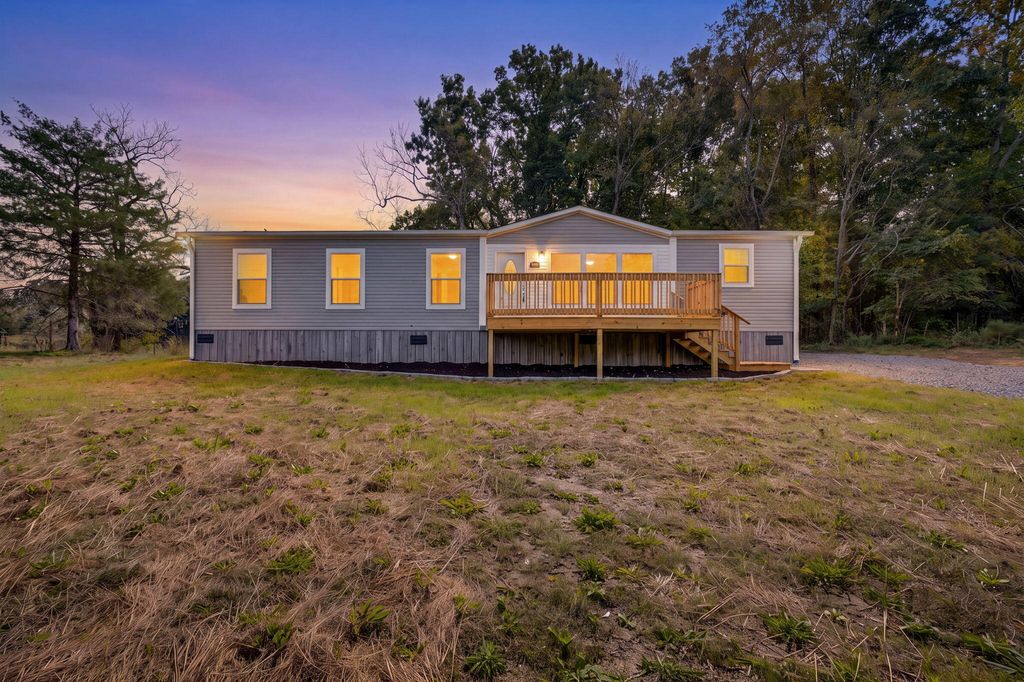 VA 3.75% AssumableSave -$830/mo
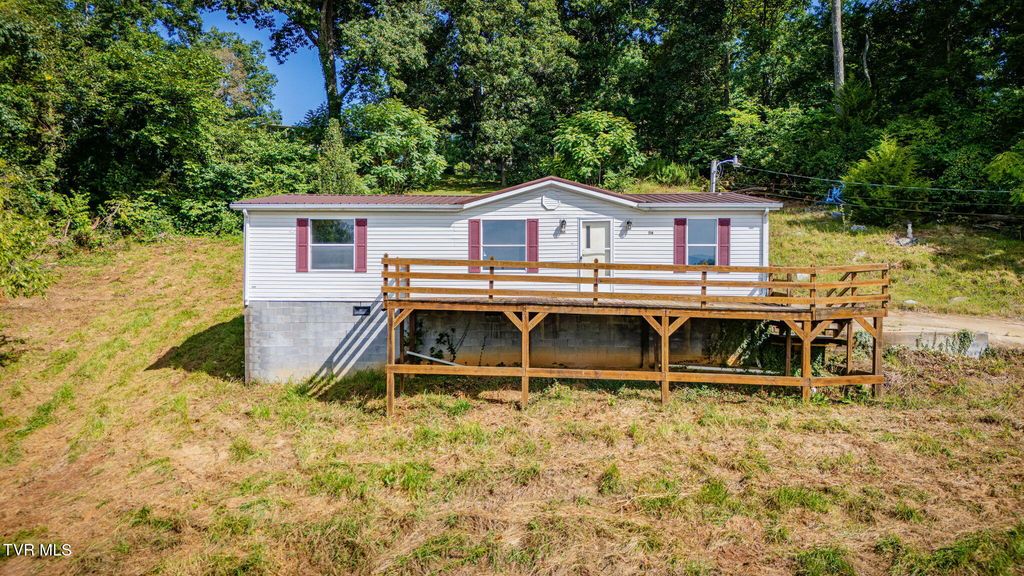 VA 2.75% AssumableSave -$507/mo
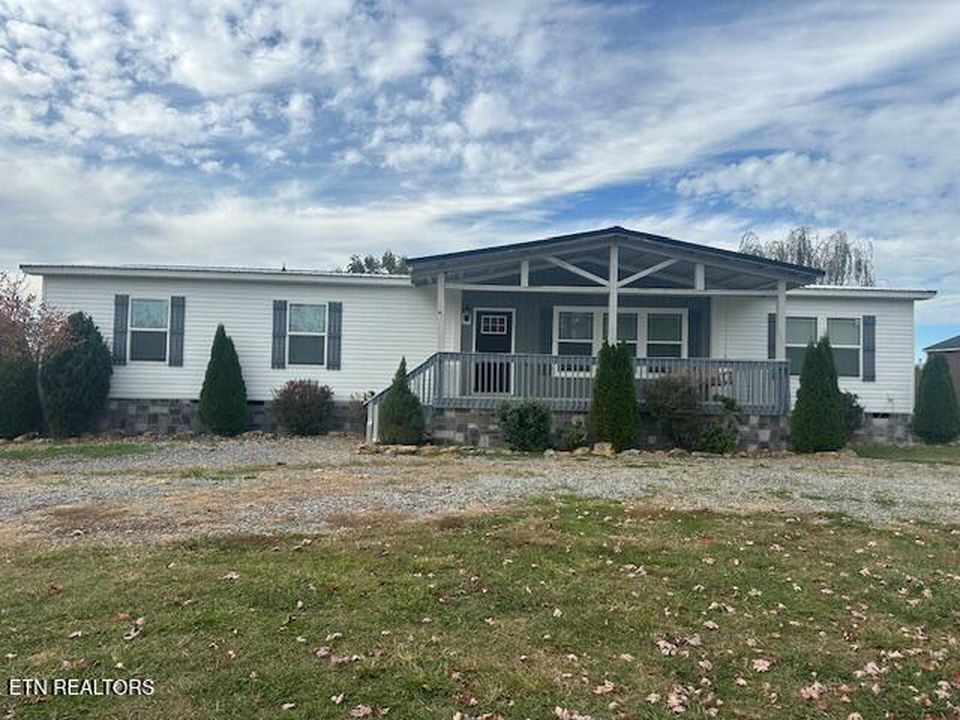 USDA 2.85% AssumableSave -$1,381/mo
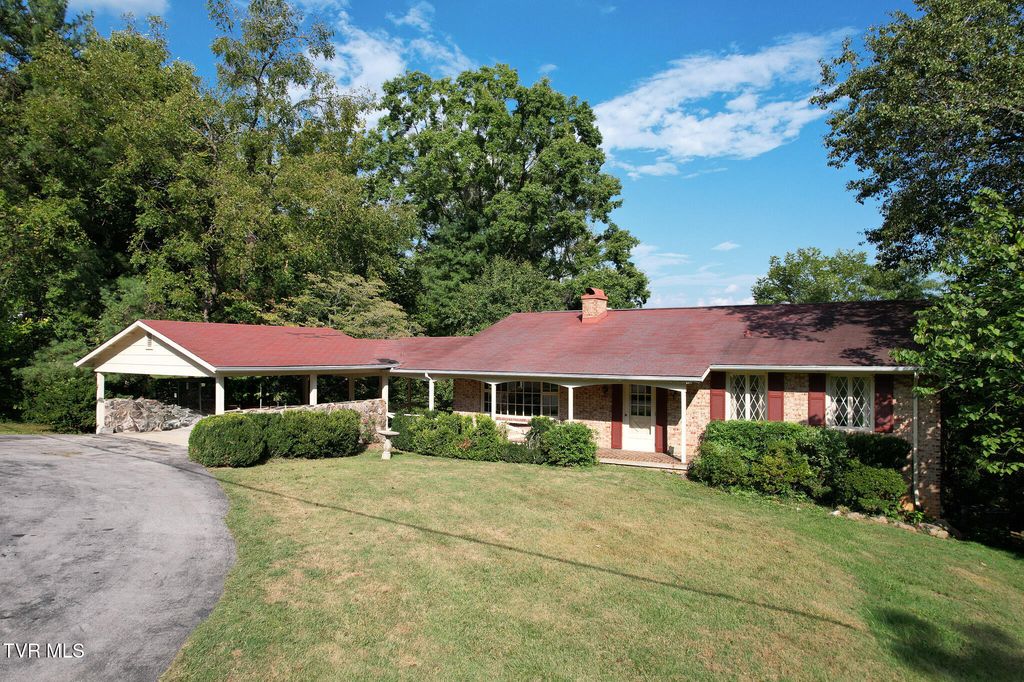 FHA 3.75% AssumableSave -$943/mo
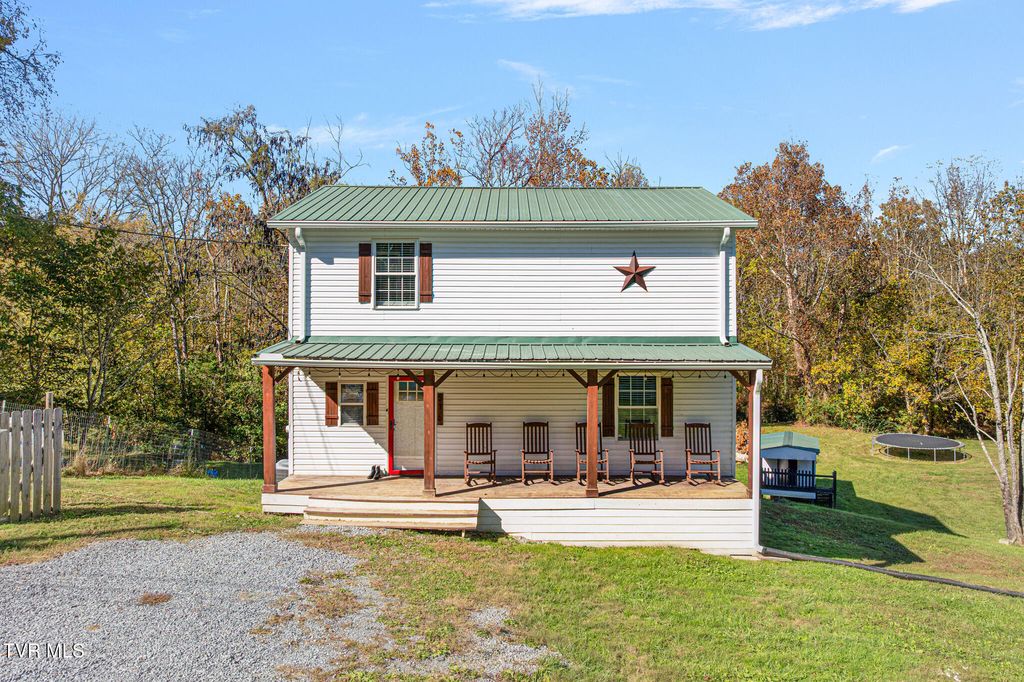 USDA 2.85% AssumableSave -$1,241/mo
 FHA 2.75% AssumableSave -$1,049/mo
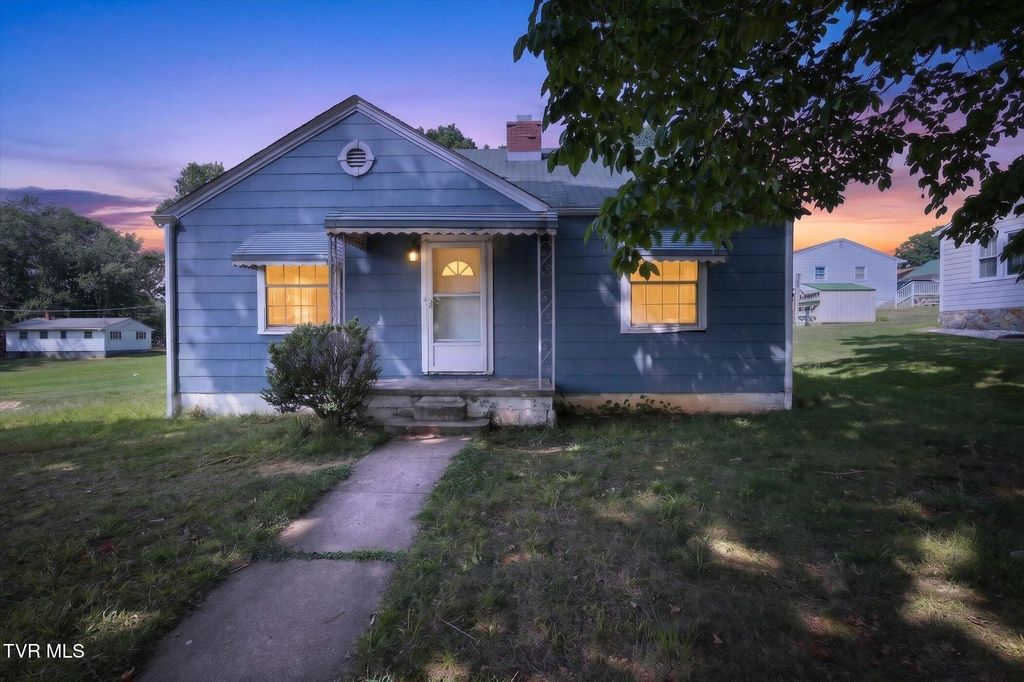 VA 3.75% AssumableSave -$444/mo
 VA 2.75% AssumableSave -$2,006/mo
 VA 2.85% AssumableSave -$657/mo
Frequently Asked Questions: Assumable Loans in Greeneville, TN
Which loans are assumable in Greeneville, TN?
All government-insured FHA, VA, and USDA residential mortgages in Greenevilleare assumable under federal guidelines, allowing a qualified buyer to take over the seller's interest rate and remaining loan balance.
How do Greeneville buyers finance the equity gap?
If a home in Greeneville is listed at $475,000 with a $315,000 assumable balance, the equity gap is $160,000. You can either bring cash or pair the 1st mortgage with a 2nd-position loan from participating Greeneville lenders so you only bring 5%–10% down.