Assumable Mortgage Homes for Sale in Alabama (AL)
Instead of paying a 7%+ market mortgage rate, take over a homeowner's existing 2.25%–4.25% FHA, VA, or USDA loan in Alabama. Compare estimated remaining loan balances, equity gaps, 2nd-position financing options, and county property tax estimates (Alabama County · 0.41%/yr avg in Alabama).
Are You a Loan Officer in Alabama (AL)?
Receive every homebuyer FHA/VA assumption & 2nd-position equity gap loan inquiry in Alabama (AL) directly in your inbox, plus rotate in the featured lender slot on listings.
Featured Assumable Mortgage Homes in Alabama
Click any home below to customize your cash down, 2nd loan, and monthly payment in the interactive calculator.
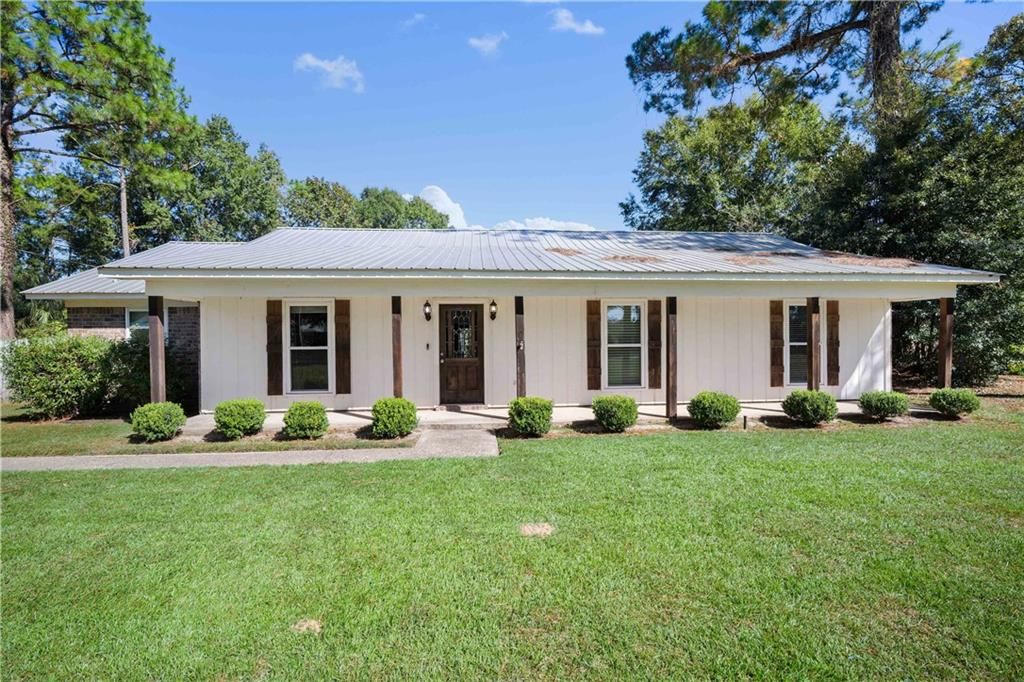 VA 3.75% AssumableSave -$782/mo
 VA 2.85% AssumableSave -$871/mo
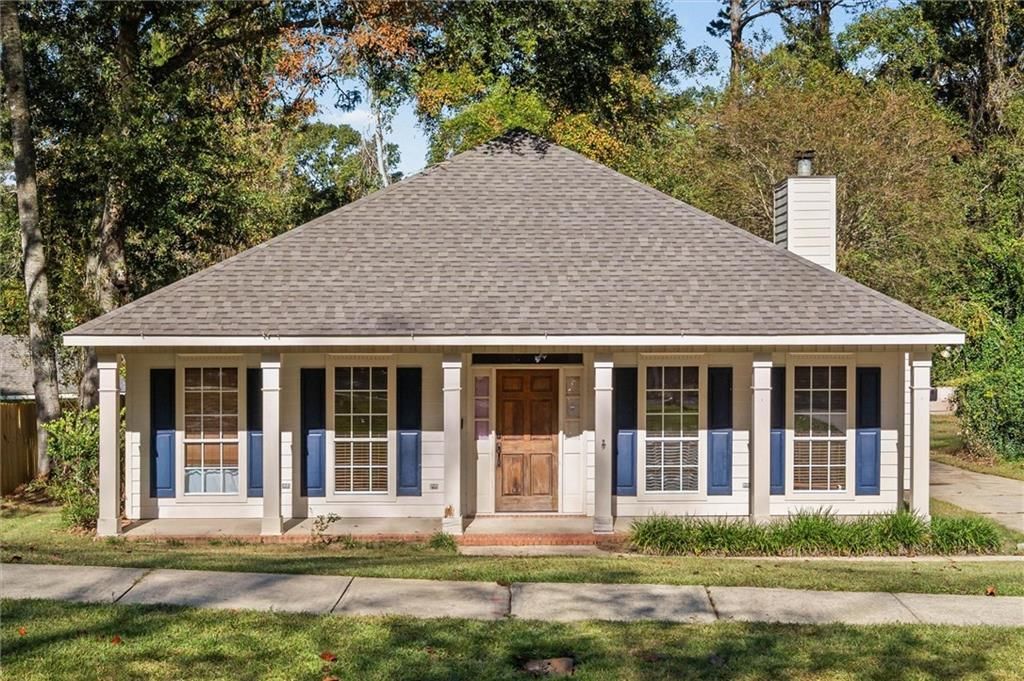 VA 2.75% AssumableSave -$844/mo
 VA 3.75% AssumableSave -$829/mo
 VA 2.75% AssumableSave -$860/mo
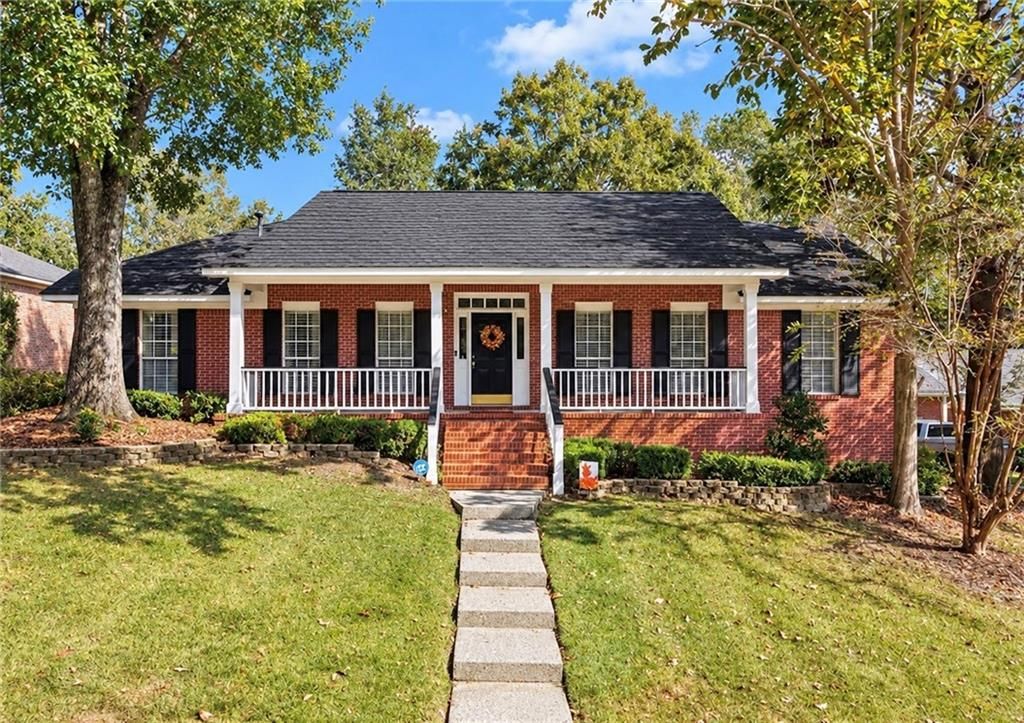 VA 2.85% AssumableSave -$1,155/mo
 FHA 3.75% AssumableSave -$1,596/mo
 VA 2.85% AssumableSave -$694/mo
 VA 2.75% AssumableSave -$678/mo
 VA 3.75% AssumableSave -$572/mo
 VA 2.75% AssumableSave -$1,025/mo
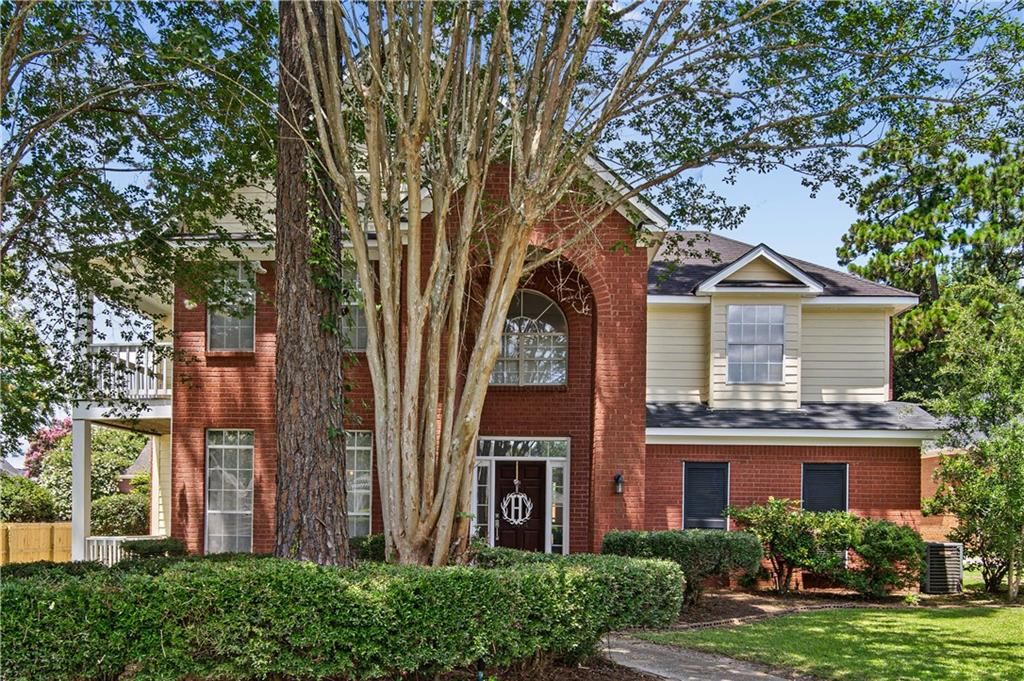 VA 2.85% AssumableSave -$1,304/mo
Browse Assumable Homes by City in Alabama
30 Alabama MarketsHow Assumable Mortgages Work in Alabama (AL)
Every government-backed FHA, VA, and USDA mortgage in Alabamais legally assumable by a credit-qualified buyer. Instead of originating a brand-new 30-year mortgage at today's market rates, you take over the seller's exact interest rate and remaining term.
Because Alabama homeowners have paid down their principal and gained home equity since 2020–2022, buyers bridge the gap between the purchase price and the remaining loan balance using cash or a 2nd-position loan (keep as little as 5% cash down).
When you request a quote on any Alabama listing on RateTakeover.com, participating assumption and 2nd-lien lenders in that zip code compete for your business so you get the lowest blended monthly payment.